Tracing Fraudulent Transfers of Digital Assets Under New York's Uniform Voidable Transactions Act
By StonePath Investigations, LLC · NYS-licensed PI firm · CAMS, CFE, TRM CI
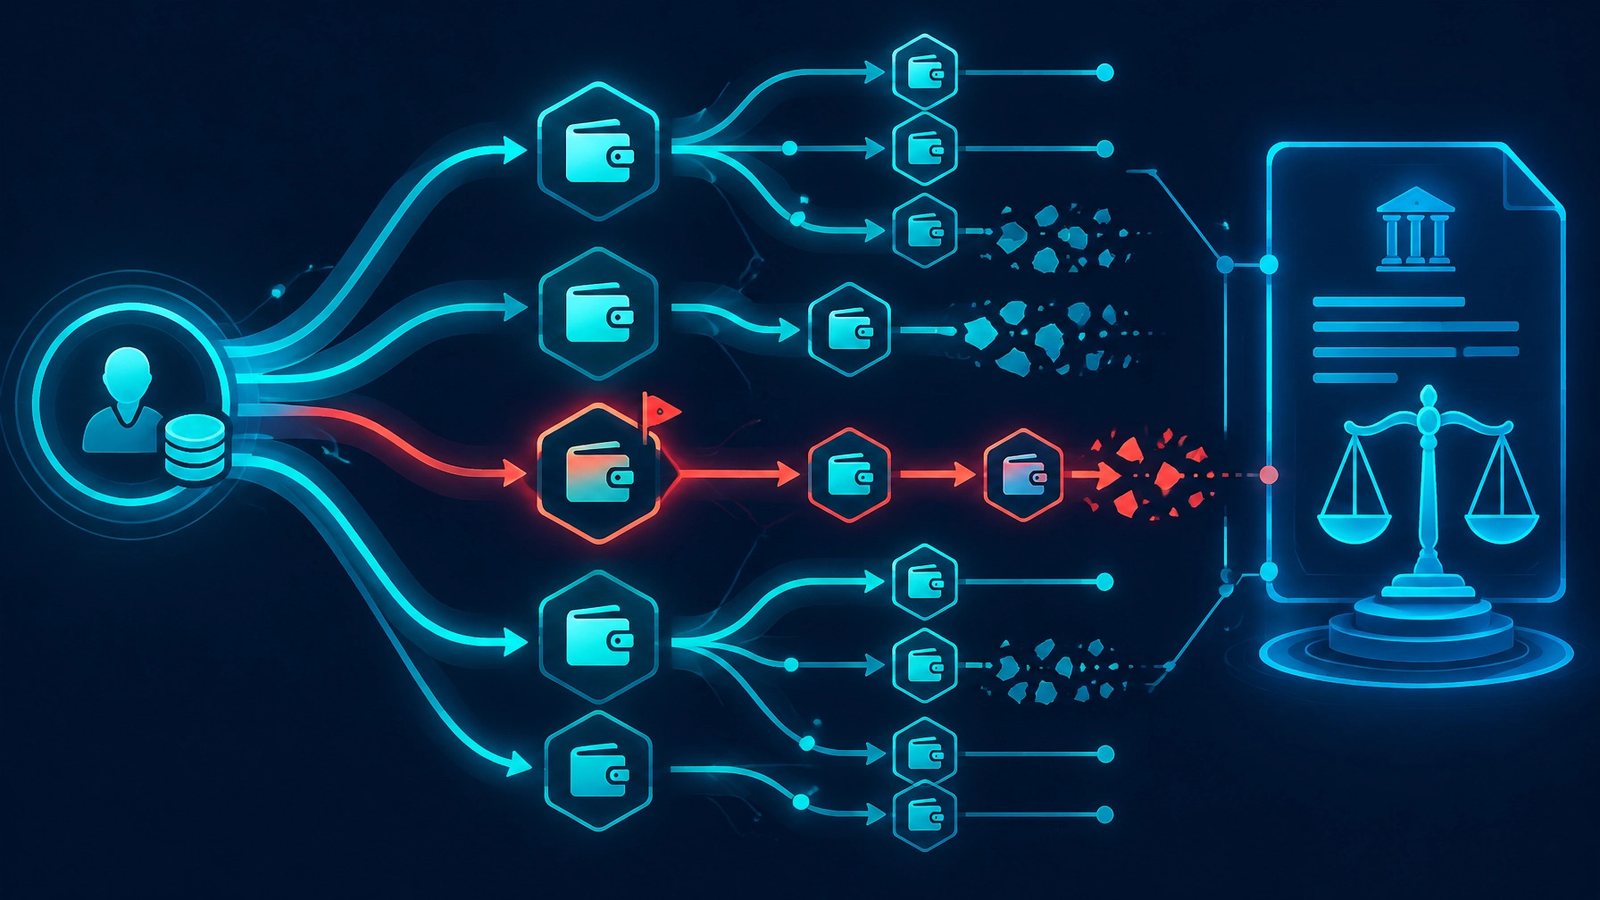
When a judgment debtor or a failing business moves crypto, the transfer is permanent, timestamped, and public. That is exactly why digital assets are both the best and the worst asset class for a fraudulent-transfer claim: the evidence of movement is irrefutable, but the legal questions around intent, value, and insolvency still have to be proven the old-fashioned way.
New York's Uniform Voidable Transactions Act, the UVTA, sits at Debtor and Creditor Law Article 10. It is the statute a creditor's-rights or bankruptcy litigator reaches for when a debtor stripped assets, digital or otherwise, before the judgment or the filing. This article maps the UVTA framework onto on-chain evidence: what the blockchain proves, what it cannot prove, and how a tracing file supports each element of the claim.
The two theories, briefly
The UVTA recognizes two claim types, and they demand different evidence.
Actual-fraud transfers are the first category: under Debtor and Creditor Law § 273(a)(1), a transfer is voidable as to a creditor if the debtor made it with actual intent to hinder, delay or defraud any creditor. The inquiry is the debtor's state of mind, and because intent is rarely admitted, courts infer it from objective badges of fraud.
Constructive-fraud transfers are the second: § 273(a)(2) makes a transfer voidable where the debtor received no reasonably equivalent value and was engaged or about to engage in a business or transaction for which its remaining assets were unreasonably small, or intended to incur, or reasonably should have believed it would incur, debts beyond its ability to pay as they came due. No proof of intent is required. Note what that subsection does not contain: it does not turn on insolvency as such. The insolvency-based theory for a creditor whose claim arose before the transfer sits in a separate provision, § 274(a), and it reaches further, allowing avoidance where the debtor was insolvent at the time or became insolvent as a result, or where the transfer left remaining assets unreasonably small, or the debtor intended or believed it would incur debts beyond its ability to pay. The financial-distress tests differ between the two, so counsel should identify the specific subsection in play rather than treating "constructive fraud" as one theory.
One drafting note: the UVTA deliberately removed the word "fraud" from the constructive provisions to separate statutory voidable-transfer claims from common-law fraud. That means a constructive-fraud complaint is not a fraud pleading, and intent allegations are unnecessary, and sometimes counterproductive, in that count.
Badges of fraud, translated into on-chain patterns
Courts evaluating actual intent look for objective markers. The familiar badges map onto blockchain behavior with unusual precision:
Insider transfers. Value routed to wallets associated with principals, family members, or affiliated entities, especially newly created addresses.
Transfers after threats. Movement beginning shortly after a demand letter, litigation filing, or audit inquiry; on-chain timestamps make the sequence objective.
Concealment. Fragmentation of value across many addresses, rapid chain-hopping, bridging to obscure networks, or conversion into assets held through intermediaries.
Retention of control or benefit. Round-trip transactions where value leaves one controlled wallet and returns to another, or peeling patterns where a portion is spent and the remainder stays with the same controller.
Disproportionate consideration. Assets swapped to a nominee for nominal value, or treasury tokens sold to an insider far below market.
Insolvency indicators. Transfers made while liabilities mounted, payroll or vendor obligations went unpaid, or the entity was already in default.
The analytic question for each: what was approved on the business side, and what actually moved on the chain? The gap between those two records is where fraudulent-transfer cases are built.
What the chain proves, and what it cannot
The blockchain is an objective, immutable record of the transfer event itself. For each transaction, the ledger establishes:
The transaction hash and block height, fixing the time and place of the transfer;
The sending and receiving addresses;
The asset, amount, and token contract;
The service touchpoints involved, including exchange deposits, bridges, and swap contracts;
The chronology across addresses, networks, and conversions.
That is a complete answer to what happened to the asset. It is not, by itself, an answer to the three questions the UVTA actually asks:
Who controlled the wallet? Attribution requires off-chain evidence: exchange KYC records connecting an account to a person, device or login evidence, IP and session data, communications, and business records. An address is not a defendant.
Was the transfer for reasonably equivalent value? The ledger shows what went out. It does not show what came back in legal substance. Value analysis requires the transaction documents, consideration actually paid, the parties' business relationships, and market context.
Was the debtor insolvent, or rendered insolvent, at the relevant time? Insolvency is a balance-sheet and cash-flow question answered by accounting records, liabilities, and financial condition, correlated with the transfer dates the ledger establishes.
A disciplined tracing report therefore does two things at once: it fixes the objective transfer facts beyond dispute, and it identifies precisely which off-chain records are needed to complete each element. The report should not pretend the ledger proves intent. It should make the ledger's facts usable for the analysis that proves everything else.
Building the evidentiary record
A UVTA tracing file that supports litigation typically contains:
A transaction schedule: every relevant hash, timestamp in UTC, asset, amount, addresses, and network;
A flow narrative connecting the debtor's known wallets to the destination addresses, including exchange touchpoints where value converted to fiat or consolidated;
Clustering analysis with stated methodology and confidence levels, distinguishing observation from inference;
Valuation documentation for the transferred assets, with dates aligned to the transfer events;
An insolvency timeline correlating transfers with the debtor's financial condition;
The badges-of-fraud mapping, tying each on-chain pattern to the objective marker courts recognize.
Preservation discipline matters here as much as analysis. Transfers can be initiated the moment a debtor learns of a claim, and exchange retention policies vary. Preservation letters to the relevant exchanges, and early collection of the debtor's own records through discovery, protect the record before it moves again.
Remedies and procedure under the UVTA
The UVTA gives a creditor tools calibrated to the problem. A voidable transfer can be avoided to the extent necessary to satisfy the creditor's claim, with the recovered asset applied toward the obligation. Courts may grant attachment or injunction to restrain further disposition while the claim is pending, and may appoint a receiver where appropriate. The statute also provides for costs, a change from prior practice that counsel should verify against the current text rather than assume.
Limitations periods matter disproportionately in crypto cases, because the transfers themselves are often discoverable late. The governing provision is § 278, which extinguishes the claim unless action is brought within four years of the transfer or obligation. For an actual-intent claim under § 273(a)(1), the outside date extends to one year after the transfer was or could reasonably have been discovered, whichever is later. For a constructive claim under § 273(a)(2) or § 274(a), the four-year period runs without a discovery extension, and the § 274(b) theory carries a one-year period. That asymmetry has a practical consequence: the claim that survives late discovery is the intent claim, which is precisely the one that needs badges-of-fraud evidence anchored to dates. Verify the current text before pleading; misciting the period is an avoidable gift to the defense.
Discovery strategy pairs naturally with the tracing file: requests targeting wallet addresses, exchange account records, device inventories, and communications about transfers; third-party subpoenas to exchanges for KYC files and transaction logs; and, where assets sit on a cooperative platform, a preservation notice before anything else.
Where this practice is heading
Digital assets did not create fraudulent-transfer litigation. They made the transfer record permanent, objective, and globally visible, which raises the evidentiary bar the debtor must clear to hide anything, and raises in equal measure the precision a creditor's analyst must maintain.
The disciplined sequence is the same as it has always been: characterize the claim, assemble the objective record, test each element against the evidence available, and keep the difference between what the ledger shows and what the law requires in full view. For counsel building that record, a structured methodology for organizing on-chain and off-chain evidence is what turns a flow chart into proof. The approach StonePath Investigations applies to crypto investigations, preparing litigation-ready transaction documentation in cryptocurrency matters, follows that discipline.
Honest limits
Constructive claims turn on value-equivalence and solvency facts that only the record can establish. Actual-intent claims may face heightened pleading requirements in New York practice, requiring specific facts rather than conclusory allegations, so the complaint's badges-of-fraud allegations should be anchored to identified transfers and dates from the tracing file. And a voidable-transfer claim is a remedy against property, not a guarantee of collection: if the assets have been dissipated into non-cooperative rails or jurisdictions, even a successful avoidance action may recover little. This article is educational context for practitioners, not legal advice, and the statute's current text is the controlling authority.
If a debtor moved digital assets before a judgment or filing, the transfer record is permanent but the off-chain evidence is not. Contact StonePath Investigations, LLC to discuss litigation-ready forensic blockchain analysis for fraudulent-transfer claims.
Schedule a Free ConsultationReferences
- New York Debtor and Creditor Law § 273, Transfer or obligation voidable as to present or future creditor, New York State Senate consolidated laws
- New York Debtor and Creditor Law § 278, Extinguishment of claim for relief, the limitations provision discussed above
- New York Debtor and Creditor Law § 271, Insolvency, the statutory definition governing the insolvency-based theory
- New York Debtor and Creditor Law § 274, Transfer or obligation voidable as to present creditor, the separate provision for pre-existing creditors
- New York Debtor and Creditor Law § 270, Definitions, including the definition of transfer applied to digital assets
- New York Debtor and Creditor Law § 279, Governing law, the choice-of-law rule that determines which state's avoidance law applies to a cross-border transfer
- Jones Day, “Uniform Voidable Transactions Act Adopted in New York,” April 2020
- Quinn Emanuel, “New York Enacts New Fraudulent Transfer Law”
- Olshan, “Client Alert: New York's Uniform Voidable Transactions Act,” January 2020
- Warner & Scheuerman, “Fraudulent Conveyance Claims Under New York's Voidable Transactions Act,” May 2026